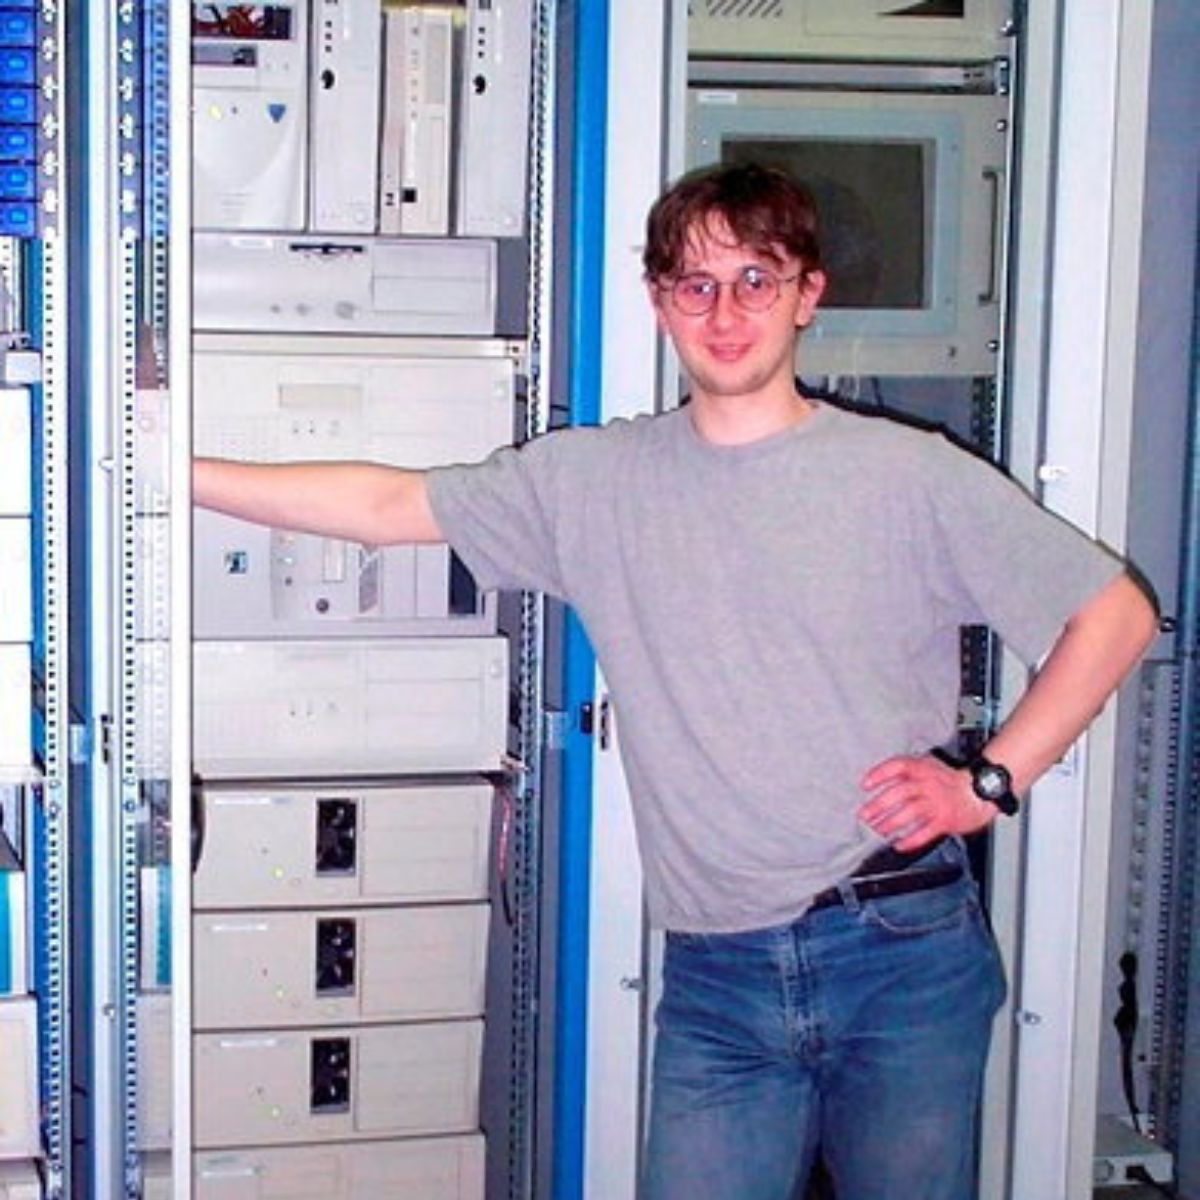
Octave Klaba, founder and president of OVHcloud — the Polish student who built a European cloud giant — appeared before the French National Assembly on September 30 to discuss data centers, cloud computing, and digital sovereignty. His testimony raised a thesis that goes beyond how much money governments spend on cloud: Europe has technology providers, but many don’t reach the scale needed to fund product development, hire talent, and compete for years against Amazon, Microsoft, or Google.
Key takeaways from Octave Klaba’s view of European cloud, in 30 seconds
- The French government’s public cloud spending reached €84 million in 2025; OVHcloud billed €33 million of that, according to Klaba.
- The European Commission awarded €180 million over four to five years to four European providers, while Klaba puts AWS and Azure’s annual business with the Commission at around €1.7 billion.
- European providers’ share of their own market fell from 29% in 2017 to 15% in 2022.
- Klaba is calling for 5% to 15% of digital public procurement to go to European companies.
- His most business-focused argument is about scale: a cloud product may need just 10-15 people whether it generates €10 million or €1 billion in revenue.
The hearing took place before the National Assembly’s Economic Affairs Committee and raised a question that tends to get lost behind the sovereignty debate: how does a European tech company reach the size it needs to compete?
Klaba explained that OVHcloud already exceeds €1 billion in annual revenue and employs around 3,500 people. He presented his own company’s trajectory as an example of a business that grew for years with little outside capital, but argued the real problem shows up when a company needs to accelerate and go up against rivals with far more capital, customers, and investment capacity.
Market data backs up that argument. Synergy Research Group estimates that European cloud service providers saw their share of the European market shrink from 29% in 2017 to 15% in 2022. It has stayed around that level since, while Amazon, Microsoft, and Google together control close to 70% of Europe’s cloud infrastructure market.
Public money can be a lever, but scale is a different story
One of the most striking figures from the hearing was the contrast between European public procurement and the business that U.S. hyperscalers already generate.
Klaba explained that the European Commission has allocated €180 million over four or five years to a sovereign cloud contract split among four European providers. OVHcloud is among the winners, alongside other European players.
Klaba himself put that figure in perspective: by his numbers, AWS generates around €1.2 billion a year from the European Commission, and Azure another €500 million. That contrast doesn’t mean all of that spending could automatically shift to European providers, but it does show the gap in scale between a single support initiative and the volume of business the big U.S. providers already handle.
In France, the French state’s public cloud procurement reached €84 million in 2025, according to figures cited during the hearing. Klaba said OVHcloud was the top provider, with €33 million. For a company with over €1 billion in revenue, that figure is still relatively small.
There’s an important nuance here: a National Assembly report on digital dependency notes that the public cloud market handled by UGAP, France’s public procurement agency, grew from €20 million in 2022 to €84 million in 2025. That shows the growth of that procurement, but it doesn’t mean the €84 million represents the French government’s entire cloud spending.
Klaba’s proposal is to reserve between 5% and 15% of digital public procurement for European providers. His argument is that sustained demand would let these companies raise revenue, invest in product, and reach a scale that would later make it easier to compete outside the public sector too.
It wouldn’t just be a matter of buying European services. The logic he laid out is that a company needs enough customers to fund the layers that are harder to build when the business is small.
Talent becomes a matter of size
This is where the hearing gets most interesting for the tech sector.
Klaba explained that building a cloud software product can require a relatively small team once it’s up and running. By his example, the same product can run with about 10 or 15 people even as revenue grows from €10 million to €100 million or even €1 billion.
The result is that a large company can spend a smaller share of its revenue maintaining that product and use the freed-up margin to hire more people in sales, R&D, or marketing.
That scale effect also affects the salaries a company can offer. A European tech company with €100 million in revenue may be competing for the same engineers, product leads, or sales talent as a company worth several billion, but with a very different financial structure to do it.
David Carrero, co-founder of Stackscale (Aire Group), agrees with that diagnosis and points specifically to the ability to attract talent. In his assessment of the hearing, he notes that a provider with enough scale can afford salary packages that are hard for a smaller European company to sustain.
Carrero adds another factor: the migration away from VMware may be creating an immediate opportunity for European providers. Broadcom has changed VMware’s licensing model since acquiring the company, and CISPE has documented price increases reported by its members reaching between 800% and 1,500% in some cases. In March 2026, the association also filed a new complaint with the European Commission over VMware’s licensing practices.
That shift could accelerate the search for alternatives based on open virtualization. Proxmox, KVM, Ceph, and ZFS are part of that technology landscape, although migrating away from VMware isn’t automatic and can require changes to infrastructure, tooling, and processes.
Carrero believes this existing demand could be a faster path for European providers to gain scale than waiting solely for public procurement rules to change.
Data centers: the other bottleneck is electricity
Klaba also extended the scale problem to physical infrastructure. As he explained to the National Assembly, building a 100- to 200-megawatt data center in France can take four to five years.
His comparison with the United States was even starker. There, 2- or 3-gigawatt facilities are already being planned, while Klaba believes a single 1-gigawatt data center at one site will be very difficult to deploy in France and Europe given the restrictions tied to power, water, emissions, and permitting.
OVHcloud’s founder pointed to his own company’s experience in Roubaix as an example. The company acquired buildings located 200 to 700 meters apart and went through the regulatory process for each facility separately. The problem arises when separate buildings end up being treated as a single site for regulatory purposes, which raises compliance requirements.
The specific figure of €5 million to €6 million associated with that case should be understood as an estimate tied to Klaba’s testimony, not a general cost that applies to any data center.
The business, however, can justify enormous investment. Klaba calculated during the hearing that a cloud provider can generate between €15 million and €20 million in annual revenue for every megawatt of data center capacity. That’s a reference provided by Klaba himself, not a universal financial standard for the industry.
RAM and hardware are also entering the equation
The cloud sovereignty debate doesn’t end with software, either. OVHcloud builds its own servers, and Klaba explained that the company runs two factories, one in northern France and another in Canada.
The state of the memory market is complicating that strategy. In recent statements, OVHcloud has warned of sharp increases in the price of RAM and storage, tied to manufacturing capacity shifting toward products linked to artificial intelligence.
During the hearing, Klaba noted that RAM prices had multiplied several times over in a year. A figure of six to nine times also appears in public statements linked to OVHcloud, though it should be understood as the cost the company was seeing in its own purchases, not a uniform price hike across every memory module on the market.
TrendForce, for its part, forecast in July 2026 a quarterly price increase of 13% to 18% for server DRAM contract prices in the third quarter, within a market it still described as undersupplied.
That adds a second layer to the European debate: having data centers and in-house software isn’t enough if the server supply chain depends on components manufactured outside Europe.
Klaba’s testimony leaves a broader question than simply choosing between AWS, Azure, Google Cloud, or OVHcloud. Europe’s problem is achieving enough scale in capital, talent, customers, infrastructure, and supply chain so that local companies can fund products for years and compete in a market where rivals already start with a huge customer base.
Public procurement can provide demand, but the migration away from proprietary technologies, the growth of AI, and the need for new infrastructure are also creating opportunities outside public budgets. The challenge is turning that demand into companies large enough to sustain investment when the next technology cycle again demands more capital.
Frequently Asked Questions
What did Octave Klaba say about Europe’s cloud industry?
OVHcloud’s founder argued that Europe needs to scale up its cloud providers to compete with U.S. hyperscalers. Among his proposals is reserving 5% to 15% of digital public procurement for European companies.
How much did the French government spend on public cloud in 2025?
During the hearing, a figure of €84 million was cited for the French government’s public cloud spending in 2025. Klaba said OVHcloud was the top provider, with €33 million.
How does VMware relate to opportunities for European providers?
VMware’s licensing changes following Broadcom’s acquisition have driven up costs reported by some CISPE members and are pushing organizations to explore alternatives. That migration could create demand for open virtualization technologies and European providers.
Why does scale matter so much for a cloud provider?
According to Klaba, a cloud product can need around 10-15 people to maintain even as its revenue grows from €10 million to €1 billion. Greater scale lets a company spend a smaller share of revenue on that team and put more resources into sales, R&D, and expansion.
via: LinkedIn
