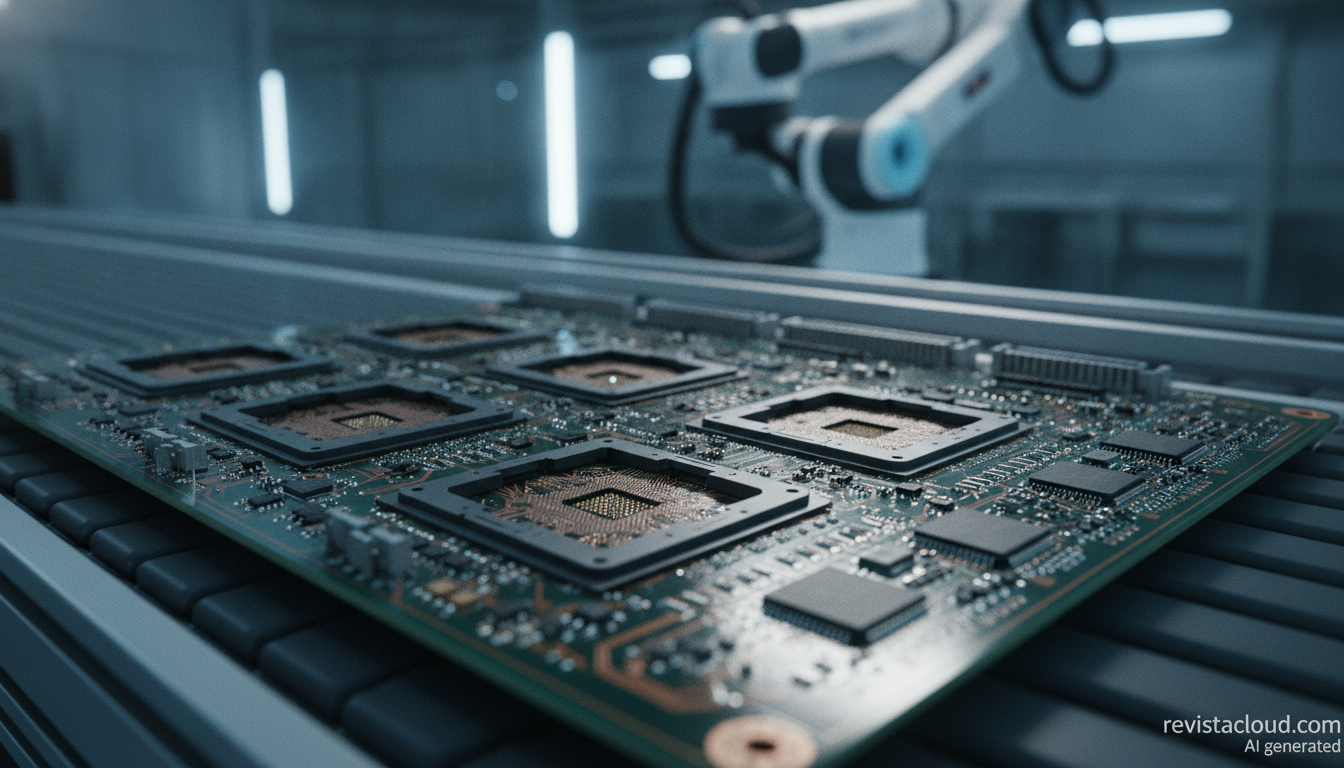
The jump from 1.6T to 3.2T optical modules is starting to change something that stayed relatively stable for years: the printed circuit board (PCB) itself that connects the components inside the module. The next generation will require lines and spacing of just 10-15 microns, more layers and lower-loss materials, which significantly raises the manufacturing difficulty and could concentrate orders among a very small group of manufacturers. A DIGITIMES report published on October 6 points to the SAP manufacturing process leaving the supply of these PCBs in the hands of just three companies.
3.2T optical module PCBs: the key facts in 30 seconds
- Optical modules are moving from 800G to 1.6T and already preparing the next generation at 3.2T.
- 3.2T is expected to need lines and spacing of 10-15 microns, compared with around 20-30 microns at 1.6T.
- The jump forces higher PCB precision and the use of more advanced SAP or mSAP manufacturing processes.
- The current market identifies Unimicron, Zhen Ding and Compeq as the manufacturers with relevant capabilities for these PCBs.
- The first 3.2T modules are expected around 2028, so much of this technology is still in development and qualification.
The reason behind the change is the growth of AI workloads. Large data centers need to move ever more data between GPUs, CPUs, ASICs and switches, and optical links have become an essential part of that infrastructure.
This evolution isn’t simply a matter of doubling a speed figure. As the module moves from 800G to 1.6T and then to 3.2T, the speed of the electrical signals that have to travel across the small PCB inside the transceiver also increases. That shrinks the margin available for losses, interference and deviations in trace dimensions.
As a result, the PCB stops being a relatively conventional module component and starts requiring processes closer to those used in higher-density technologies.
From 800G to 3.2T: Each Generation Demands Finer Lines
Data published across the industry shows a fairly clear progression. 400G modules work with trace widths and spacing of roughly 40-50 microns. At 800G that range drops to around 30-40 microns, and at 1.6T it sits at roughly 20-30 microns. For 3.2T, estimates point to 10-15 microns.
That reduction has a direct consequence: manufacturing through conventional PCB methods becomes less and less adequate.
A traditional PCB is made by starting from a copper layer and removing material through etching processes. As traces get narrower, the so-called undercut, or lateral etching during the process, makes it harder to keep exactly the designed dimensions.
Modified semi-additive manufacturing processes, known as mSAP (modified Semi-Additive Process), allow traces to be built with greater precision starting from much thinner copper layers and controlled deposition and etching processes.
That’s why mSAP has become a relevant technology with the arrival of 1.6T modules. An industry report published in June placed Unimicron, Zhen Ding and Compeq among the leading suppliers of mSAP PCBs for high-speed optical modules.
The jump to 3.2T raises the bar even further. Some industry estimates point to boards with 18 or more layers, lower-loss M9 materials and 10-15 micron lines. These figures are industry forecasts, not a universal specification for all 3.2T modules.
The Board Is Also Changing Materials and Structure
Shrinking the lines isn’t the only challenge. As signals work at ever-higher frequencies, losses from the PCB material itself start to carry more weight.
800G and 1.6T designs have already increased the use of low-loss materials and higher-grade laminates. In the transition to 3.2T, various supply-chain analyses anticipate further material improvements, including M9-class laminates and structures with more layers.
The complexity of the board itself is also increasing. Data compiled by the Taiwan Printed Circuit Association puts 400G modules at around 10 layers, 800G at 12-14, and 1.6T at 14-18. For 3.2T, designs are expected to reach as many as 18-20 layers.
The result is a difficult combination: more layers, narrower traces, lower-loss materials and tighter manufacturing tolerances, all within an optical module that keeps very limited dimensions.
Having an mSAP line isn’t enough on its own. The manufacturer needs to control exposure, copper thickness, layer-to-layer alignment, microvias, electroplating and trace uniformity. It also needs to achieve a high enough manufacturing yield for the product to be viable at scale.
Three Manufacturers Take the Front Line
This is one of the most interesting points in the new landscape. DIGITIMES notes that the push toward 3.2T is tightening the SAP process and narrowing the group of suppliers capable of meeting the requirements.
The market had already identified three Taiwanese manufacturers as the main players in PCBs for high-speed optical modules: Unimicron (欣興), Zhen Ding Technology (臻鼎-KY) and Compeq Manufacturing (華通). An analysis published in June by Economic Daily cited precisely these three companies as manufacturers with relevant capabilities for optical transceiver PCBs and mSAP.
That doesn’t mean they’re the only manufacturers in the world capable of producing any 3.2T PCB. Other manufacturers are developing mSAP and related technologies, and the market itself keeps expanding capacity.
In fact, industry sources also mention companies such as Tripod, WUS Printed Circuit and other manufacturers investing in these technologies. Some already work with 800G and 1.6T modules or are preparing capacity for the next generations.
That’s why the figure of three suppliers should be read as a reference to the group of manufacturers with established capabilities and relevant positions in this segment, not as a definitive list of every potential 3.2T PCB supplier.
The difference can matter a great deal for large customers. Producing a sample is not the same as achieving certification, hitting the required yields, and keeping production stable for months. Taiwan’s PCB makers have already drawn outside investment in this space, as shown by Amazon’s recent stake in Gold Circuit Electronics, another Taiwanese maker of boards for AI servers.
Manufacturers Are Already Preparing the Next Generation
This evolution is already showing up in company moves.
Zhen Ding presented 800G, 1.6T, XPO and NPO products in September at SEMICON Taiwan 2026 and has said that its orders for optical communication products are growing, driven mainly by high-speed 1.6T boards. The company has also indicated that customers are reserving capacity for 2027 and that it aims to become one of the world’s leading suppliers of high-end optical PCBs.
Compeq, for its part, mentions in its 2025 corporate documentation the development of 800G, 1.6T and 3.2T optical products, along with improvements to mSAP processes and 20/20-micron line capability. That shows the company is already working on the next generation, though it doesn’t mean a specific 3.2T product is already in mass production.
In Zhen Ding’s case, the company itself has shown a product sheet that includes 1.6T/3.2T optical modules, while its current 1.6T products are already entering production.
The industry’s situation fits a timeline in which 1.6T is moving from introduction to large-scale production during 2026, while 3.2T remains in development, sampling and qualification. Coherent, for example, places 3.2T in development on its transceiver roadmap, while other companies are already showing prototypes or evaluation products. This broader push against the Taiwanese PCB supply chain, already under strain from AI demand for CCL and ABF materials, is reshaping the roadmap for the whole industry.
The Real Bottleneck May Be in Manufacturing
The race toward 3.2T doesn’t depend solely on having an optical design capable of reaching 3.2 Tb/s. The entire electrical path connecting the DSP, the optical components and the host system has to preserve signal integrity.
That’s where the PCB takes on an importance that, until just a few years ago, could easily go unnoticed.
A difference of just a few microns can affect a trace’s electrical behavior. Copper roughness, dielectric thickness, layer-to-layer alignment and via geometry all factor into the final result.
As a result, increasing 3.2T production capacity isn’t simply a matter of installing more PCB lines. It requires sufficiently precise exposure and drilling equipment, suitable materials, and the experience needed to maintain good yields.
The market is already showing signs of this pressure. The manufacturers that dominate mSAP are expanding capacity while new competitors try to break in. At the same time, customers are beginning to qualify suppliers well ahead of mass production.
For AI data centers, this has a practical consequence. The evolution of accelerators and switches can generate demand for higher speeds, but that demand can only turn into deployable systems if the entire interconnect chain can manufacture the components with enough volume and reliability.
The jump to 3.2T, expected by various players over the coming years, thus turns a small, seemingly secondary part into an important component of the AI supply chain. And the finer the PCB has to be, the fewer manufacturers will be in a position to produce it with the necessary yield.
Frequently asked questions
What changes in a PCB for a 3.2T optical module?
Forecasts point to lines and spacing of 10-15 microns, more layers and lower-loss materials. This requires more precise manufacturing processes than those used in earlier generations.
What is mSAP?
mSAP stands for modified Semi-Additive Process. It’s a PCB manufacturing technique that allows finer, more precise circuits to be built than traditional etching methods.
Who are the three main suppliers of optical PCBs?
The industry identifies Unimicron, Zhen Ding Technology and Compeq as three of the leading manufacturers with relevant capabilities for high-speed optical module PCBs. This shouldn’t be read as a closed list of every potential 3.2T supplier.
When will 3.2T optical modules arrive?
Industry forecasts place the first commercial products around 2028, although various prototypes, demonstrations and qualification processes are already underway. The final timeline will depend on data center platforms and the maturity of the entire supply chain.
